

Written by the AutoMagToday Content Team | Reviewed by Rubi Chauhan, Insurance Advisor, AutoMagToday.com | Last updated: November 2026
Quick Answer
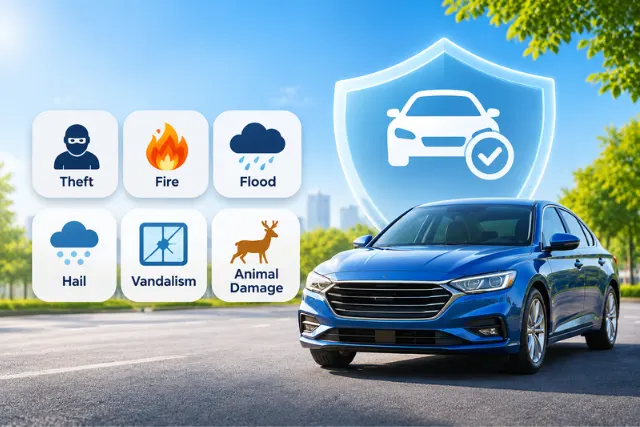
If you are wondering what is comprehensive car insurance, it is coverage that protects your vehicle against damage caused by events other than accidents involving a collision. This can include theft, fire, hail, flooding, vandalism, falling objects, and animal-related damage. It helps cover the cost of repairs or replacement, up to your vehicle’s actual cash value, after deducting your policy’s deductible. However, it does not cover collision damage, third-party liability, or regular wear and tear.
Comprehensive car insurance pays for damage to your car that doesn’t come from a crash. That includes theft, hail, fire, flooding, vandalism, a tree limb coming down on the roof, or a deer running out in front of you on a two-lane road. It sits next to collision coverage on most auto policies, and you’ll normally pay a deductible when you use it.
The name is a little misleading, to be fair to the people who buy it. Plenty of drivers assume “comprehensive” means their car is covered for anything. It isn’t. It’s one part of a policy with a fairly narrow job, and once you understand that job, the rest of your policy makes a lot more sense.
Policies vary from company to company and state to state, so treat this as a general guide and your own policy as the final word.
What Is Comprehensive Car Insurance?
Comprehensive coverage pays to repair or replace your own vehicle when something other than a collision damages it. Insurance people often call it “other than collision” coverage, or OTC.
It protects you from things you mostly can’t control. You can drive carefully for thirty years and still walk outside to a smashed window.
When a claim is approved, the insurer pays for repairs, or for the car’s value if it’s a total loss, after subtracting your deductible. The payout is usually capped at actual cash value. That’s what your car was worth the moment before it was damaged.
Say you leave your car in the driveway overnight and a spring storm drops golf-ball-sized hail on it. The body shop quotes $2,800 for the roof and hood. With a $500 deductible, you’d cover the first $500 and the insurer would generally pay the other $2,300.
What Does Comprehensive Car Insurance Cover?
The comprehensive losses named in the National Association of Insurance Commissioners’ (NAIC) consumer guide include: theft, vandalism, hail and other weather damage, broken glass, fire, explosion, earthquake, falling objects, contact with animals. Floods and windstorms are also included. Hailstorms can cause significant damage to a vehicle’s roof, hood, and windows. Learn more about whether car insurance covers hail damage and what to expect when filing a claim.
Understanding what is comprehensive car insurance also means knowing which unexpected events your policy may cover. It generally protects against damage caused by situations beyond your control, such as severe weather, theft, fire, and vandalism.
This is the coverage you’d turn to if your car was stolen in an apartment complex parking lot, if a neighbor etched his keys down the sides, or if a tornado hurled a tree at your windshield.
This is the coverage that would pay when your car was washed away in the flood or set ablaze in the garage. Ramming a rogue cow in a country road is included here too – a common shock to many.
Windshields are a special case. A windshield claim from a rock thrown on the interstate is usually an all-inclusive claim, though some policies will isolate the glass from an all-encompassing policy, and some states mandate that insurance providers forgo a windshield deductible.
If your windshield has a crack or chip, you may also need to consider vehicle safety requirements. Here’s what you should know about passing a car inspection with a cracked windshield.
What Does Comprehensive Car Insurance Not Cover?
- Comprehensive won’t pay for damage from hitting another vehicle or an object while you’re driving. It doesn’t cover injuries you cause, or damage you do to someone else’s car, fence or storefront.
- Worn tires and faded paint are ordinary wear and tear, so they’re out too.
- Mechanical failure is another common mix-up.
- If your transmission gives out at 120,000 miles, comprehensive won’t help. If it fails because the car sat in floodwater, that’s a different story, because the flood is the covered event.
- A laptop stolen from inside the car usually isn’t an auto claim at all. Homeowners or renters insurance typically handles that. If personal belongings are stolen from your parked vehicle, your renters policy may provide protection depending on its terms. Find out whether renters insurance covers theft from a car and what limitations may apply.
- Other coverages fill these gaps. Collision pays for your car after a crash, and liability pays for the harm you cause other people.
- Depending on your state, medical payments or personal injury protection (PIP) helps with medical bills.
- Uninsured motorist coverage protects you when the at-fault driver doesn’t carry enough insurance.
Comprehensive vs. Collision Insurance: What’s the Difference?
The easiest way to keep them straight is that collision is for crashes and comprehensive is for most other damage. The Insurance Information Institute (Triple-I) splits them the same way.
| Comprehensive usually covers | Collision usually covers |
| Theft and vandalism | Hitting another vehicle |
| Hail, wind and flood | Hitting a pole, fence or guardrail |
| Fire | Pothole damage |
| Falling objects | Rollovers |
| Hitting an animal | Single-car accidents |
When comparing these two options, remember that comprehensive car insurance covers non-collision incidents, while collision coverage handles damage caused by accidents. Knowing what is comprehensive car insurance can help you understand why both coverages are often included in an auto insurance policy.
This is where it gets a little odd with deer. Normally, hitting a deer is a comprehensive claim. But if you swerved to avoid a deer and hit the guardrail instead, that’s a collision claim, and some insurers may take that into consideration when they calculate your rates. It’ll look like the same repair when you take it to the body shop.
Is Comprehensive Insurance the Same as Full Coverage?
No. You won’t find a policy actually called “full coverage.” Dealers, lenders and agents use the phrase, and it usually means liability, collision and comprehensive bundled together, plus whatever else your state requires.
So comprehensive is part of full coverage, not the whole thing. To see exactly what you have, pull up the declarations page of your policy, which lists every coverage and deductible you’re paying for.
How Does a Comprehensive Insurance Deductible Work?
The deductible is the portion of a covered claim you pay yourself, and it comes off the top of what the insurer pays. If a vandal causes $3,000 in damage and your comprehensive deductible is $500, you’d generally get $2,500, assuming the whole loss is covered.
Most insurers offer comprehensive deductibles of $250, $500 or $1,000, sometimes higher. The NAIC notes that raising yours usually lowers your premium, though you’ll pay more when something actually happens. The NAIC’s auto insurance consumer guide also explains how deductibles affect premiums and what drivers should consider when choosing their coverage.
My advice is to pick a number you could pay from savings next week without scrambling. For some people that’s $1,000, for others it’s $250.
Before choosing a deductible, consider how much you could comfortably pay out of pocket after a covered incident. Knowing what is comprehensive car insurance and how its deductible works can help you select a coverage option that fits your budget.
How Much Does Comprehensive Car Insurance Cost?
The cost also depends on the type of protection you choose. Once you understand what is comprehensive car insurance and what it covers, you can compare quotes from different insurers to find a suitable premium and deductible.
- It comes down to the value of your vehicle, your ZIP code, where you park, your driving history, your deductible and your insurer.
- To get an estimate, Triple-I has reported the average total premium at slightly more than $134 a year, far less than the average for a collision. That’s from an older post about industry data, though, and won’t be in your quote.
- If you’re shopping for a pickup in north Texas, where the nightly downpour is a new pickup, a 10-year-old sedan parked in a Seattle garage will cost more to insure.
Is Comprehensive Car Insurance Required by Law?
No, in most situations. State minimum requirements tend to be liability coverage, which provides protection for other individuals. According to the NAIC, state laws typically don’t mandate physical damage coverage such as comprehensive and collision.
Do Have a Financed Car? Do You Require Full Coverage?
At the other end of the spectrum, there’s your lender. When you’re financing or leasing, the contract is nearly always going to demand full and collision coverage until the loan is repaid, because the bank has invested money in your ride. If you let your coverage drop, the lender can buy it and send you the bill. You’re not going to like the sticker price.
If you’re purchasing a vehicle through financing, understanding the car insurance requirements for financed vehicles can help you avoid coverage gaps and meet your lender’s conditions.
Is Comprehensive Car Insurance Worth It?
For most people driving a car with real value, yes. Deciding whether to buy it becomes easier when you understand what is comprehensive car insurance, the risks it protects against, and how much you could receive after a covered loss.
- Start with what the car is worth. If it’s an old commuter worth $2,500 and you carry a $1,000 deductible, the most you’d ever collect is about $1,500, and a couple of years of premiums could eat into that.
- Then think about where you live. Hail comes every year across Texas, Colorado and the Plains, Gulf Coast drivers deal with hurricanes and flooding, and deer collisions are common through much of the Midwest and Pennsylvania.
- The last question is simple. If your car disappeared tomorrow, could you replace it without real financial pain?
- If not, comprehensive is probably worth keeping. And if the car is financed, the lender has already made the decision for you.
Does Comprehensive Insurance Cover Theft?
Yes. Comprehensive generally covers theft of the car itself, subject to your deductible and policy terms. If the car is never recovered, the insurer typically pays its actual cash value minus the deductible. If police find it damaged, comprehensive can pay for the covered repairs.
Does Comprehensive Insurance Cover Hail Damage?
Generally, yes. Hail is one of the most common comprehensive claims in the country. Dented roofs, hoods and trunks are the usual damage, along with cracked glass. Your deductible still applies, and on an older car, a bad enough storm can lead the insurer to total it rather than repair it.
How Do You File a Comprehensive Insurance Claim?
Ensure everyone is safe and then photograph and film everything-plenty-before anyone moves anything, or starts clearing up. If it’s a theft or a vandalism, call the police.
Now, call your insurer by telephone, on-line or via its app and tell them what happened, when and where. They might have an appraiser or want a repair estimate from you. When the claim is authorised you write a cheque to the shop for your deductible and the insurer pays for repairs or, if the car is written off, a settlement.
The Bottom Line
Now that you understand what is comprehensive car insurance, remember that it protects your vehicle against unexpected non-collision damage, including theft, fire, hail, flooding, vandalism, falling objects, and animal-related incidents. It does not cover damage caused by a collision or injuries and property damage involving other people.
Know what your policy excludes, choose a deductible you can handle and compare the cost of the premium to the value of your car before you buy or renew.
Frequently Asked Questions
Does comprehensive insurance cover hitting a deer?
Usually, yes. Swerving into something else instead usually makes it a collision claim.
Does comprehensive insurance cover flood damage?
Generally, yes. Flood damage to your car usually falls under comprehensive, even though standard homeowners policies don’t cover floods.
Does comprehensive insurance cover engine failure?
Not by itself. Normal mechanical breakdowns aren’t covered unless a covered event, like a flood or fire, caused them.
Does comprehensive insurance cover windshield damage?
Often, yes. Rock chips and cracks are commonly handled under comprehensive, and some states or policies waive the deductible for glass repairs.
Can I have a comprehensive without collision?
Many insurers allow it, and it’s a common choice for older cars or cars in storage. Lenders almost always want both.
Disclaimer
This article is intended for general informational and educational purposes only. Insurance coverage, exclusions, deductibles, claim procedures, and premium rates may vary depending on the insurance provider, policy terms, and state regulations. The information provided should not be considered legal or financial advice. Always review your policy documents and consult your insurance provider to confirm the coverage available to you before making a purchase or filing a claim.